
Inside the financial plumbing that keeps global markets running
Stanford Professor Darrell Duffie reflects on four decades studying financial markets, tracing lessons from the 2008 crisis through to today’s central bank policy debates
Behind every loan, bond and share trade sits a layer of market infrastructure that most people rarely think about – until it stops working. That infrastructure decides whether firms can raise capital, whether banks can lend and whether governments can fund the basics that keep an economy running, according to Darrell Duffie, the Adams Distinguished Professor of Management and Professor of Finance, Emeritus, at Stanford University’s Graduate School of Business.
Over a career spanning four decades, Prof. Duffie’s research has shaped how economists, regulators and industry understand the infrastructure underneath financial markets, from repo markets to credit risk to the response to the 2008 financial crisis. His work on the networks connecting banks, investors and central banks has informed the way regulators track risk as it moves through the financial system, and he continues to speak directly with central bankers, investment banks, hedge funds and insurers as part of his research process.
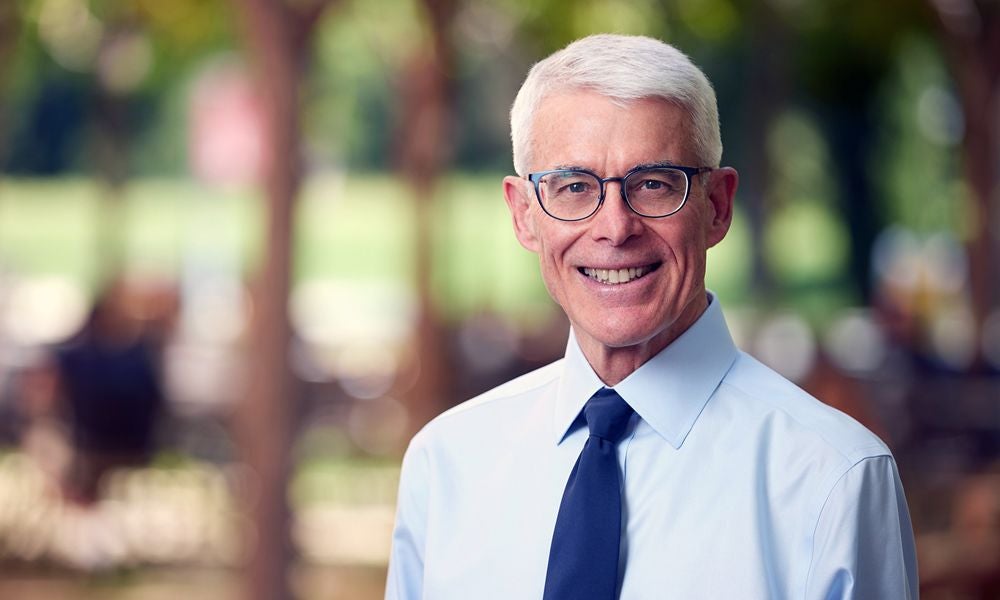
UNSW Business School’s Senior Deputy Dean Research & Enterprise, Professor Karin Sanders and Professor of Finance, Alexandre Jeanneret, spoke with Prof. Duffie about the less visible dimensions of finance, what the 2008 crisis revealed about risk, and the choices he has made across a research career that spans academia, central banks and industry.
Prof. Sanders: You’ve often described financial markets as having plumbing that most people never see. Why does this infrastructure matter, and what do people get wrong about it?
Prof. Duffie: Plumbing is a good metaphor for a lot of what happens in financial markets. When you walk to the kitchen sink and turn on the tap, you’re shocked if the water doesn’t come out or isn't clean. It’s not what you expect, and it’s not the norm. It’s the same with financial markets. The plumbing beneath the structure is assumed to work every day; when it doesn’t, it can cause serious problems. People go into shock when what they thought was true no longer works. The example is the 2008 financial crisis, when the plumbing stopped working. Bond markets weren’t working, banks weren’t lending, and some influential macroeconomists were shocked that finance actually has a role to play in the macroeconomy. It’s not simply a tube through which the money flows without any friction.
From the perspective of people outside financial economics, the impression of financial markets is that they’re a place to speculate, to buy low, sell high, and take risks for a return. That’s true, but it’s a small part of the picture. When we see stocks and bonds, they’re not there as vehicles for speculation. They’re there because firms need to raise money to run factories and hire workers. They’re there because governments need to raise funds to defend the country and build roads and bridges. Much of the functionality of financial markets is to provide households and firms with capital and ways to bear or reduce risk. Derivatives markets are for reducing risk; you need someone on the other side to take it.
"These are places where bond investors provide their bonds to others so they can get cash for a while. I call it the dark matter of finance"
DARRELL DUFFIE
Prof. Sanders: What has been the piece of your own research that changed the way you think about financial markets?
Prof. Duffie: Around every ten years through the course of my career, I’ve come to the incorrect conclusion that I’m finally getting a deeper understanding, and then I find out after a few more years that I hadn’t. I went through one of these moments in the early 1990s, when I started working on markets for financing securities, called repo (repurchase agreement) markets. These are places where bond investors provide their bonds to others so they can get cash for a while. I call it the dark matter of finance. About US$10 trillion of transactions happen every day in this market. It’s by far the biggest market for securities in the world, and very few people know about it. There’s no central exchange. It’s nothing like what we see on television, where everyone goes to one point, and buyers and sellers meet, whether electronically or in person. You have to call, find someone to trade with, negotiate the trade, then find someone else. It’s an arcane market, and it’s huge, and I spent twenty years trying to understand how it works.
Prof. Sanders: How did your research become part of the conversation shaping policy and industry practice?
Prof. Duffie: I think it just happens naturally if it’s going to happen, if you keep addressing problems because they’re really outstanding issues, not ones left behind by other academics for somebody else to do. That’s the way to get impact: to look at problems people are actually trying to solve in financial markets, in governments, or in corporations. There’s not much to be gained by developing relationships if you don’t have any knowledge to share. First comes the knowledge, and if it’s useful, people will get in touch with you. But most of my discussions outside academia aren’t about reaching out to tell people what I’ve learned. Most of it is that I need to know what they know. I call people at banks, central banks, hedge funds, or investment firms and tell them I’m working on a problem with a missing piece and ask if they can help me understand it. You develop relationships through that, and then people call you back and say, "We know you know about this. Can you tell us more?"
Learn more: The seven biggest risk factors affecting global financial stability
Prof. Sanders: Looking back at the 2008 financial crisis, what lessons should policymakers and business leaders take from it?
Prof. Duffie: Every crisis is special in its own way. In the case of the 2008 crisis, we learned that credit markets, especially the kind with no central exchange but a network of relationships, mattered enormously. Understanding the risks that flow on those networks turned out to be crucial to understanding how the crisis happened in the first place. The crisis initially took out a chunk of the US economy, nowhere near as big as the crater that was eventually created, because of those relationships and the contagion that followed. We learned a lot about how risk flows through the economy, and regulators around the world invested heavily in regulating and understanding those risks. A whole field was created, now called macrofinance.
Prof. Jeanneret: During the COVID crisis, we observed interventions in the secondary corporate bond markets. How do you see these markets evolving?
Prof. Duffie: Central banks expanded their balance sheets over time to support the economy to a greater extent. At one time, they would purchase only government securities; then some went into corporate bonds, and later into equities, which is quite something because central banks usually don’t take risks. Given the way our governments are structured, we often turn to central banks to get us out of trouble because they can provide almost unlimited credit to the economy. There are now suspicions that central banks are doing too much. The current chair of the Federal Reserve, Kevin Warsh, has said the Fed has been buying assets too readily and needs to reduce its size and footprint in the economy, so we may see constraints imposed on central banks. For the time being, they remain anchors of the financial system during periods of instability, and their independence is crucial. In the United States, that independence has come under question because of the role of the current presidential administration.
"Follow your passion, focus on the knowledge, and explain it as clearly as possible, without attempting to simply convince the listener or reader that it must be true"
DARRELL DUFFIE
Prof. Sanders: Business schools face growing pressure to demonstrate societal impact, while the finance field places heavy emphasis on publication in top journals. How do these two goals fit together?
Prof. Duffie: That’s a difficult balance, especially with the development of social media and the temptation to use it as a way of sharing research, which can be as impactful as publishing in a top journal. The top journals have become less a medium for communicating research over time, and more a way of signalling the quality of research, and young scholars will have to keep using that signal until there’s an alternative. I don’t see one on the horizon. In the field of financial economics, financial economists increasingly write for a general audience, not just for other financial economists, and seek to publish in the leading economics journals more broadly. I see it in my own group at Stanford: young scholars strive to publish in the top economics journals at least as much as in the top finance journals, because it gives them a wider audience. It’s increasingly difficult to know how to achieve societal impact when there are different channels for communicating research that reach different audiences.
Prof. Sanders: Your work reaches scholars, central banks and industry leaders. How do you navigate these different worlds, and how do you manage your time?
Prof. Duffie: Family comes first in our household. I have two grandchildren now, and I think of my family, and you have to have your own pursuits, reading and outdoor activities. You can’t neglect the most important things in life just to do work. As for using your work time, to tell you the truth, I can’t stop thinking about my work, no matter what I’m doing, whether I’m on a bike or talking to a friend. I’m always in the back of my mind thinking about the problem I’m trying to solve. I don’t know if that’s a good thing, but it lends itself to productivity. I try to reach out to people who are actually doing what we’re studying in financial markets, whether central bankers, investment bankers, hedge funds, or insurance companies, to find out what they’re most concerned about and how their knowledge can help me understand how to do my work. That saves a lot of time. You could bury yourself in a problem for months, and if you haven’t spoken to the right people, you might have been working on the wrong problem.
Subscribe for the latest research, analysis and insights from UNSW Business School
There’s a lot of serendipity. Suddenly, you’re invited to a meeting in New York, Washington, London, or Sydney, and you drop everything and go. Or a family member needs help, and you put everything aside. I try to use Saturday mornings to focus on one research problem, and I meet with my students frequently during the week. There’s committee work, tenure and promotions work, and lots of distractions that are important distractions you have to take care of. You have to keep processing in the back of your mind the problems you’re working on.
Prof. Sanders: Are there parts of academic work that people outside universities rarely appreciate?
Prof. Duffie: I worry that in the United States, there’s a growing trend of thinking of universities as privileged, elitist, and not contributing to society. That comes partly from the way students are admitted and the tuition fees they pay, and partly from a tendency among academics to focus on their own work rather than consider what others need to know. Academics are somewhat inward-focused in many cases, not all. I think that’s something all of us at universities should be thinking about: how to help the wider population understand that our main mission is to create knowledge for the benefit of everyone, not to serve our own interests.
Prof. Sanders: What advice would you give early-career researchers trying to connect academic work with societal impact, particularly those managing heavy workloads and young families?
Prof. Duffie: Everyone is different, but the cliche that one must follow one’s passion is important in selecting research problems. I’d also say: Understand that you’re one person in a sequence of people working in the area you’re working in, and you’re passing on knowledge. The objective is to share knowledge, and young scholars sometimes get the mistaken impression that their role is to convince others of a fact or finding. It’s not really about convincing. It’s to share and help others understand what you found, not to convince them that your idea must be true, because if you take that point of view, you develop a bias and you’re not open about the evidence both for and against the hypothesis you’re trying to explain. So: follow your passion, focus on the knowledge, and explain it as clearly as possible, without attempting to simply convince the listener or reader that it must be true.